 Aakash Yadav
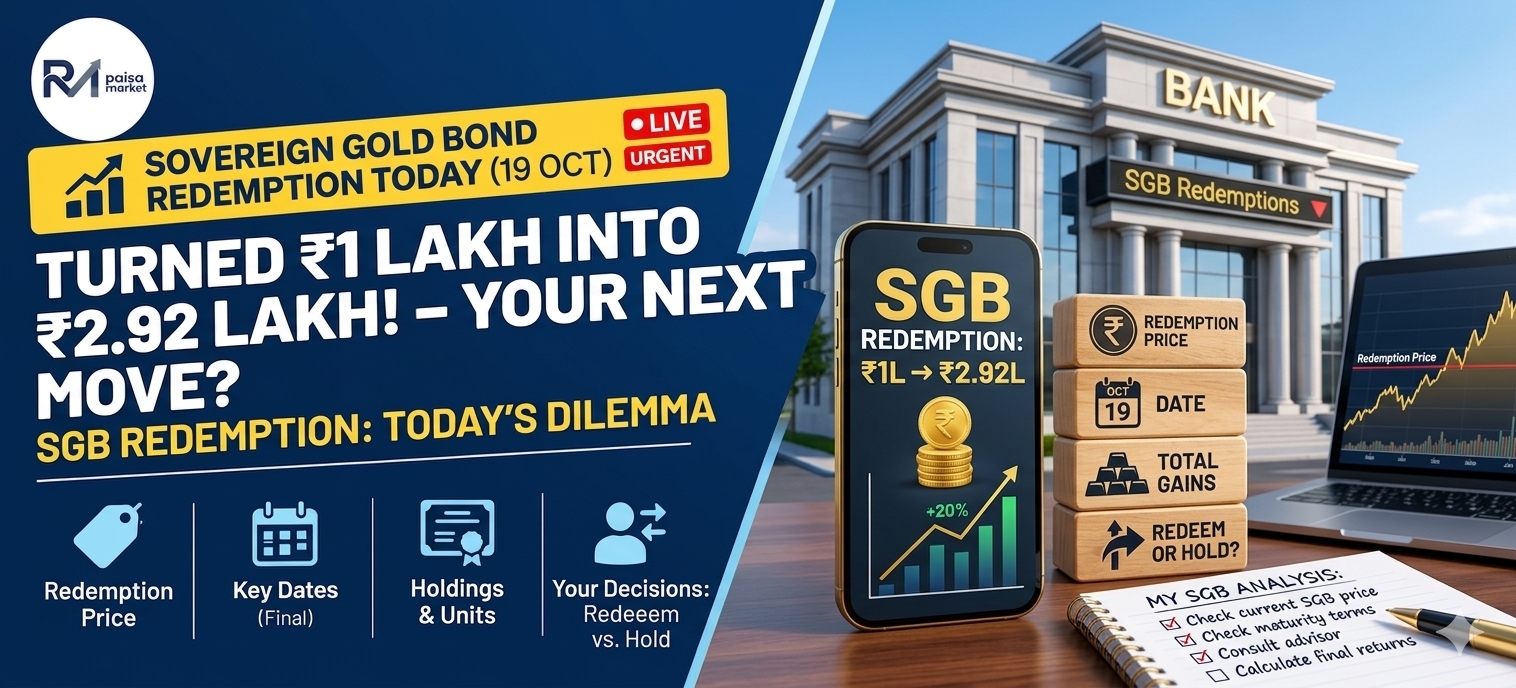
Today, 19 October 2026, is the premature redemption date for Sovereign Gold Bond 2020-21 Series VII. The Reserve Bank of India has fixed the redemption price at ₹14,614 per gram. Investors who bought these bonds online at ₹5,001 per gram are looking at an absolute capital gain of about 192%. In simple terms, a ₹1 lakh investment has grown to roughly ₹2.92 lakh on price appreciation alone.
If you hold this series, you have a clear choice today: redeem at the current price or continue holding until final maturity. The decision is not only about the attractive number. Tax treatment, your need for money, and your view on gold all play a role. Here’s a connected, practical guide that takes you through the numbers, the tax rules, the process, and the factors that should decide for you.
Table of Contents
SGB Premature Redemption Open Today – 19 October 2026
RBI has set 19 October as the premature redemption date for this tranche because 20 October is a holiday on account of Dussehra. The official redemption price are confirmed in the RBI press release on premature redemption of SGB 2020-21 Series VII.
The redemption price of ₹14,614 per unit is based on the simple average of the closing prices of 999-purity gold for 14, 15 and 16 October, as published by the India Bullion and Jewellers Association.
This series was issued on 20 October 2020. Premature redemption is allowed after five years from the issue date, on an interest payment date. That window is open today for holders of SGB 2020-21 Series VII.
How ₹1 Lakh Investment Has Grown to Around ₹2.92 Lakh
The original online issue price was ₹5,001 per gram. At today’s redemption price of ₹14,614, the capital gain works out to ₹9,613 per gram, or approximately 192%.
A quick illustration makes it clear:
- ₹1,00,000 invested at ₹5,001 per gram bought roughly 20 grams of gold.
- Redemption value today at ₹14,614 per gram comes to about ₹2,92,280.
- Capital gain is therefore around ₹1,92,280 before tax.
This figure does not include the interest you have already received. SGBs pay 2.5% interest per year on the initial issue price, credited every six months. Over more than five years, that interest adds a meaningful extra amount on top of the price gain. Offline investors who paid ₹5,051 per gram have a slightly lower percentage return (around 189%), but the absolute profit remains very strong.
Tax Rules If You Redeem Today vs Hold Till Maturity
This is the most important difference between redeeming now and waiting.
Interest received on SGBs is taxable every year according to your income tax slab. That part stays the same whether you redeem today or hold longer.
Capital gains are treated differently. If you redeem prematurely, the capital gain is taxable as long-term capital gains (the holding period is well over the required threshold). You will have to pay tax on the difference between the redemption price and your original issue price.
If you hold the bonds until final maturity, the capital gain is fully exempt from tax. This tax-free treatment at maturity is one of the biggest advantages of the SGB scheme and is the main reason many investors prefer to wait even when the current profit looks attractive.
Should You Redeem Your SGB Today or Hold Longer?
There is no single right answer for everyone. The choice depends on your personal situation.
Reasons that support redeeming today
You need the liquidity and have a clear use for the money. You are comfortable paying the capital gains tax and still locking in a large net profit. You want to book the gain and move the money into another asset or simply keep cash. You are concerned that gold prices could correct in the near term.
Reasons that support continuing to hold
You want the entire capital gain to remain tax-free at maturity. You do not need the money right now and are fine staying invested in a sovereign-backed gold instrument. You believe gold still has room to rise over the remaining life of the bond. The remaining interest payments and the final maturity value still fit your plan.
A useful way to decide is to calculate your post-tax proceeds if you redeem today and compare that figure with the tax-free amount you would receive at maturity (plus the remaining interest). For investors in higher tax slabs, the tax-free maturity route often looks cleaner even if gold prices stay flat or rise only moderately.
If you decide to redeem and still want gold exposure, physical gold or jewellery around the festive season is one alternative. Our practical checklist on whether you should buy gold before Dhanteras 2026, including purity, making charges and budget planning helps you evaluate that option carefully.
How to Redeem Sovereign Gold Bonds Today
If you have decided to redeem, the process depends on how you hold the bonds.
For bonds held in demat form, submit the premature redemption request through your demat participant, broker, or the bank through which the holdings appear. Most platforms allow this online or through a simple form.
For bonds held in physical or certificate form, approach the bank or receiving office where the bonds were issued or where you have been servicing them. You will need the bond certificate, identity proof, and bank account details for credit of the proceeds.
Requests had to be submitted within the window specified by RBI and the banks before the redemption date. If you have already submitted a valid request, the proceeds should be credited after the redemption date. If you have not submitted a request, it is now too late for this particular window.
What Happens If You Do Not Redeem Today
Missing today’s window does not mean you lose the bonds or the profit. You can simply continue holding them. The next opportunity for premature redemption will come on a subsequent interest payment date. The final maturity of the bond is eight years from the original issue date. At maturity the capital gain is completely tax-free and the principal is repaid according to the prevailing gold-price-linked formula.
In other words, not redeeming today is a perfectly valid choice. Many investors prefer to wait for the tax-free exit.
Practical Decision Checklist for SGB Holders
Before you finalise your decision, run through these four points:
- Calculate your exact capital gain using your original purchase price and the ₹14,614 redemption price.
- Estimate the tax you will pay if you redeem today, based on your current tax slab.
- Add the interest you have already received and the remaining interest you would get if you hold till maturity.
- Ask yourself whether you need the money in the near term or can comfortably leave it invested, and form a rough view on gold prices over the next couple of years.
Once these numbers and preferences are clear, the redeem-or-hold decision usually becomes straightforward.
Frequently Asked Questions on Today’s SGB Redemption
What is the redemption price for today?
₹14,614 per gram for SGB 2020-21 Series VII.
How much has a ₹1 lakh investment become?
Approximately ₹2.92 lakh on capital appreciation alone (before interest and tax) for online investors who bought at ₹5,001 per gram.
Is the capital gain tax-free if I redeem now?
No. Capital gains on premature redemption are taxable. The tax-free treatment applies only if you hold till final maturity.
Can I redeem only part of my holding?
Yes, partial redemption is generally allowed, subject to the minimum denomination rules and the process followed by your bank or demat participant.
What if I miss today’s redemption window?
You can continue holding the bonds. The next premature redemption opportunity will arise on a later interest payment date, and the final maturity remains available with full tax exemption on capital gains.
Final Recommendation – Redeem Today or Hold Till Maturity?
The numbers are strong. Turning ₹1 lakh into roughly ₹2.92 lakh on price alone is an excellent outcome. The interest received over the years adds further to the total return.
However, the tax treatment creates a real trade-off. Redeeming today means paying capital gains tax. Holding till maturity means the entire capital gain stays tax-free.
If you need the money or want to lock in the profit and redeploy it, redeeming today is reasonable — just factor in the tax. If you do not need the liquidity and can wait, holding till maturity is often the cleaner option for most investors.
There is no universal correct answer. Run the post-tax calculation for your own situation, consider your cash-flow needs, and then decide. Both redeeming and holding are sensible choices depending on your circumstances.
 contact.paisamarket@gmail.com