Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

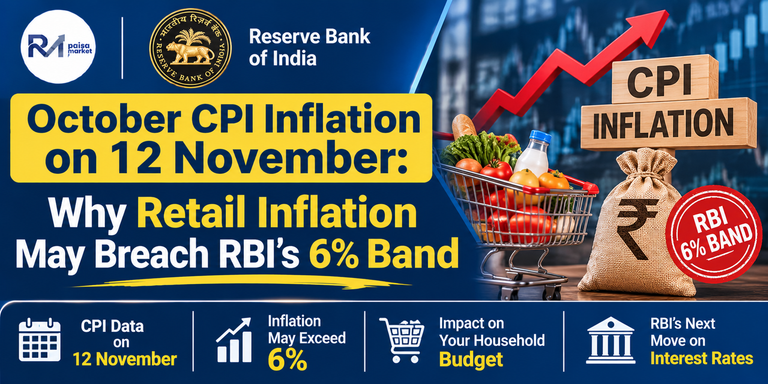
The inflation number that comes out on 12 November will be watched more closely than most monthly prints. September already pushed retail inflation to a 23-month high near 5.5%. Economists now expect October’s Consumer Price Index to land around or above 6%, which would take it outside the Reserve Bank of India’s 2–6% tolerance band for the first time in two years. That single number will shape the conversation around the December monetary policy meeting and influence how households and markets think about the next few months.
September’s 5.5% reading already signalled that price pressures were broadening. Food inflation had climbed, and core measures were no longer as subdued as they had been earlier in the year. A move above 6% in October would mark the first breach of the upper tolerance band since October 2024. For the RBI, which targets 4% with a 2–6% range, such a print would confirm that the recent upturn is not a temporary blip. Markets, bond traders and households will all read it as a signal that the inflation problem has become more persistent.
Most recent surveys cluster around 6% or slightly higher. An FE poll of economists put the consensus at 6.1%. ICRA has also projected 6.1%. A Reuters poll showed a median closer to 5.9%, but nearly half the respondents still expected the number to hit or exceed 6%. The range of forecasts runs roughly from 5.8% to 6.2%. The FE survey of 11 economists, which sees October CPI at a 24-month high of 6.1% and the first breach of the RBI’s upper band in two years, is detailed in Financial Express’s report on the October CPI poll.
Food remains the main culprit. Cereals, pulses and edible oils have all seen sustained price pressure. Vegetable prices, including tomatoes, have added to the monthly momentum. The uneven monsoon and concerns about rabi sowing have kept supply-side worries alive. When food inflation moves above 8%, it becomes difficult for the headline number to stay comfortably inside the band, especially if the base from last year is less favourable.
Even if food eventually cools, core inflation (excluding food and fuel) is expected to hold near 4.5–4.6%. Services and certain non-food items continue to show firmness. Sticky core inflation is harder for the central bank to look through because it suggests that price pressures are spreading beyond agriculture. This is one reason why a single high food print is being treated more seriously than in earlier episodes.
Last year’s GST changes created a lower base in some categories. That makes year-on-year comparisons look higher even when sequential momentum is not dramatically different. Economists have flagged this distortion, which means the headline number may overstate the underlying strength of inflation to some extent. Policymakers will look through the pure base effect, but they cannot ignore a sustained move above 6%.
The RBI has already raised the repo rate to 5.50% in October and shifted its stance to calibrated tightening. A confirmed breach of the upper band in October would strengthen the case for another hike in December. We covered the exact transmission of the October 25-basis-point move into home-loan EMIs, personal loans and fixed-deposit rates in our full analysis of the RBI’s October rate hike to 5.50%.
For households the immediate impact is felt in the kitchen. Higher prices of rice, wheat, pulses, oils and vegetables stretch monthly budgets. On the borrowing side, another rate hike would eventually feed into floating-rate home loans and personal loans, though the transmission is never instantaneous. Existing borrowers on fixed rates are insulated for now; those on floating rates or planning new loans will feel the cumulative effect of the tightening cycle.
The headline CPI will dominate the first reaction, but the details matter more for policy. Watch the food versus core split, the rural-urban difference, and the sequential momentum in key categories. Any commentary from the statistics office or immediate market moves in bond yields and the rupee will give an early sense of how the December MPC is being priced.
When will October CPI data be released?
The Ministry of Statistics and Programme Implementation is scheduled to release the numbers on 12 November.
Why is inflation expected to cross 6%?
A broad-based rise in food prices — cereals, pulses, edible oils and vegetables — is the main driver, compounded by a less favourable base in some categories.
Will RBI hike rates again in December?
A print above 6% would increase the probability of another 25 basis point hike, though the final decision will also depend on the composition of inflation and the growth outlook.
Which food items are contributing the most?
Rice, wheat, pulses, edible oils and vegetables (including tomatoes) have been the primary sources of upward pressure.
How does this affect ordinary households?
Higher food prices raise monthly grocery bills immediately. Any further rate hikes will gradually increase EMIs on floating-rate loans.
If October CPI confirms a move above 6%, the RBI’s calibrated tightening stance will face its first real test. The central bank has room to look through temporary food spikes, but a second consecutive month of elevated readings, combined with sticky core, would make another rate increase harder to avoid. For households the practical reality is simpler: food prices are already higher, and the cost of new borrowing is unlikely to ease in the near term. The 12 November print will not settle the inflation debate, but it will decide how urgently the December MPC has to respond.