 contact.paisamarket@gmail.com
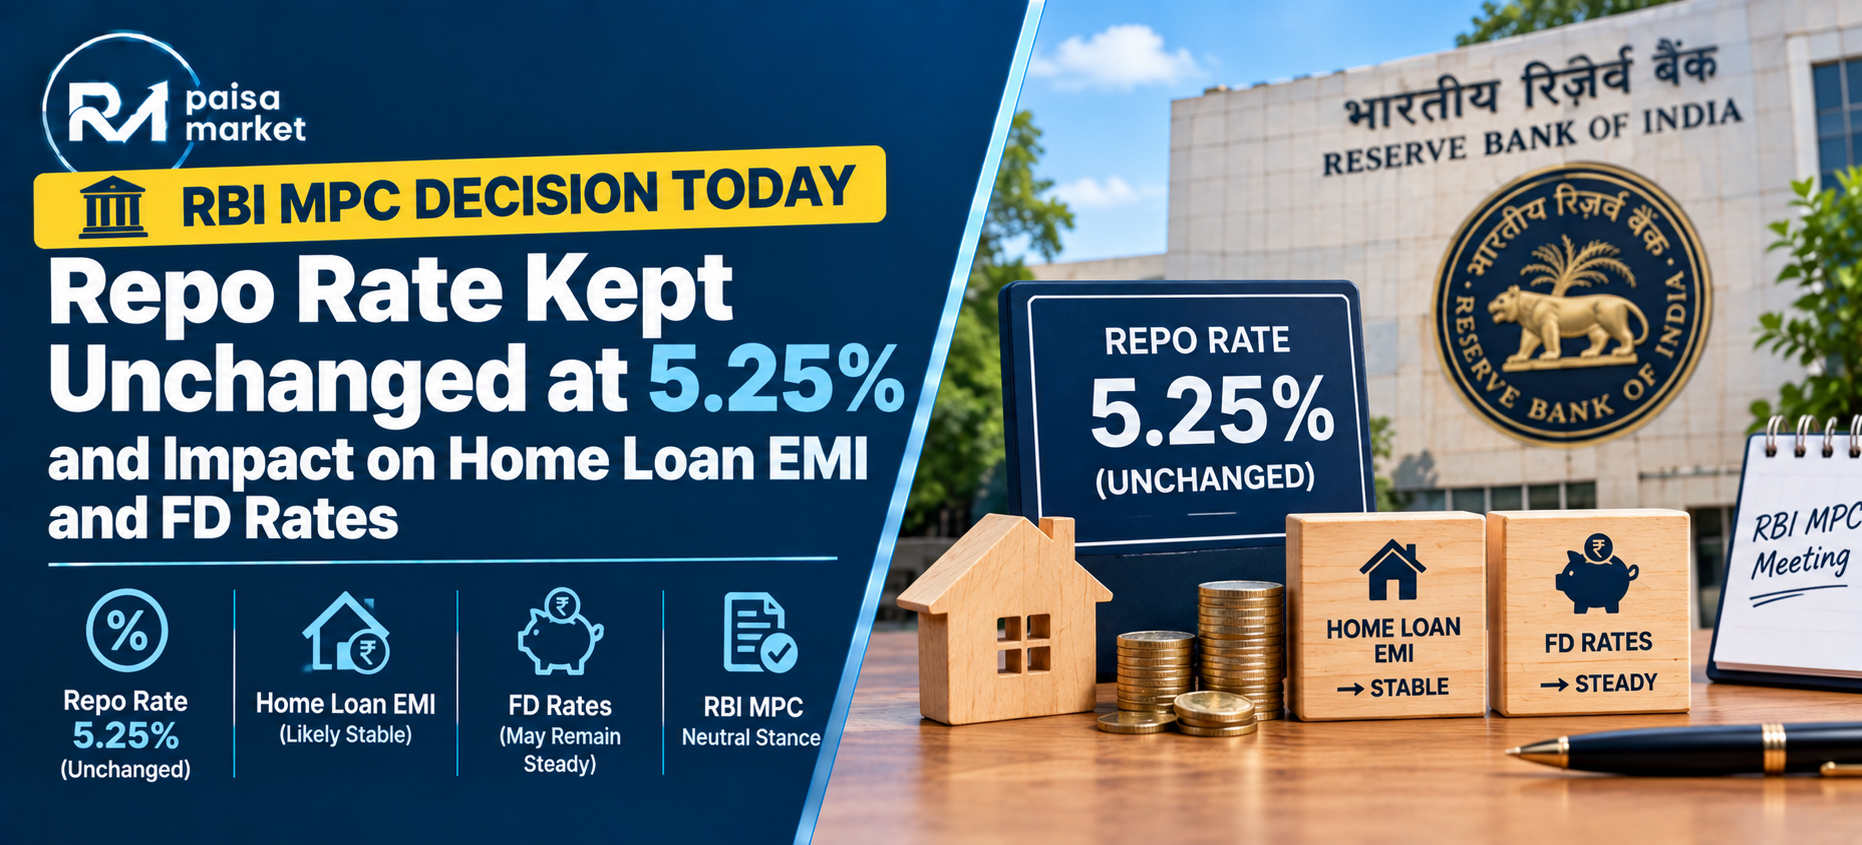
The Reserve Bank of India’s Monetary Policy Committee has announced its October decision. The repo rate has been kept unchanged at 5.25%. The policy stance remains neutral.
This means there is no immediate increase in the benchmark rate that influences loan and deposit pricing. Here’s a clear breakdown of what the decision means for your home loan EMI, personal loans and fixed deposit rates.
RBI MPC Decision Today – Repo Rate Hiked or Kept Unchanged?
What Was the Final Decision on Repo Rate
The Monetary Policy Committee decided to keep the policy repo rate unchanged at 5.25%. This continues the pause that has been in place for several meetings. The latest policy rates can be verified on the official RBI website.
Current Repo Rate After Today’s Announcement
The repo rate stands at 5.25%. The standing deposit facility (SDF) rate remains at 5.00% and the marginal standing facility (MSF) rate at 5.50%.
Key Highlights of Today’s RBI Monetary Policy
Repo Rate, SDF Rate and MSF Rate
- Repo rate: 5.25% (unchanged)
- SDF rate: 5.00% (unchanged)
- MSF rate and Bank Rate: 5.50% (unchanged)
Policy Stance Announced by RBI
The MPC retained its neutral stance. This gives the central bank flexibility to respond to incoming data on inflation and growth without committing to a fixed path of hikes or cuts.
Exact Impact of Today’s Repo Rate Decision on Home Loan EMI
Effect on Existing Home Loan Borrowers
Since the repo rate has not been increased, there is no immediate upward pressure on floating-rate home loans linked to the repo rate. Existing borrowers will not see an automatic rise in their interest rate or EMI because of today’s decision.
Impact on New Home Loan Interest Rates
New home loan rates are also likely to remain stable in the near term. Banks may still make minor adjustments based on their own cost of funds and competition, but the policy rate itself has not pushed rates higher.
How Much Can Your EMI Change
With no change in the repo rate, your EMI will not rise solely because of today’s announcement. Any change in EMI will depend on your bank’s periodic reset or other factors specific to your loan agreement.
Impact on Personal Loan Interest Rates and EMIs
Will Personal Loan Rates Rise or Stay the Same?
Personal loan rates are not expected to rise immediately as a direct result of today’s decision. Lenders may continue with their existing rates unless they have other reasons to revise pricing.
What Borrowers Should Expect
Borrowers with existing floating-rate personal loans should not see an increase linked to the repo rate. Those planning new personal loans can expect rates to stay in the current range for now.
Impact on Fixed Deposit (FD) Interest Rates
Will Banks Increase FD Rates After Today’s Decision?
An unchanged repo rate reduces the immediate pressure on banks to raise deposit rates. FD rates are likely to stay largely stable in the coming weeks, though individual banks may still tweak rates based on their liquidity needs.
With the repo rate unchanged, any movement in FD rates will depend more on bank-level decisions and the new bulk-deposit disclosure framework. See our guide on the FD rate disclosure rules from 1 October 2026.
What Depositors Can Expect in the Coming Weeks
Depositors should not expect a broad-based increase in FD rates purely because of today’s policy. Any upward movement, if it happens, will be selective and driven by competition or funding requirements rather than a policy rate hike.
How Repo Rate Changes Affect Borrowers and Depositors
Transmission of Repo Rate to Lending Rates
When the repo rate changes, banks usually transmit the impact to floating-rate loans, especially home loans linked to the external benchmark. Since there is no change today, that transmission channel remains quiet for now.
Transmission of Repo Rate to Deposit Rates
Deposit rates typically move with a lag and are influenced by overall liquidity and competition. An unchanged repo rate means banks face less urgency to increase what they pay on FDs and savings accounts.
Who Gains and Who Loses from Today’s RBI Decision
Home Loan and Personal Loan Borrowers
Borrowers benefit from the decision to keep rates unchanged. There is no fresh increase in EMIs arising from the policy announcement. This provides continuity and predictability for household budgets.
FD and Savings Account Holders
Depositors do not gain an immediate rate increase. Those looking for higher yields may need to wait for banks to act on their own or for a future policy shift.
What Should You Do After Today’s MPC Announcement
Tips for Existing Home Loan Holders
- Continue servicing your EMI as usual.
- If you have surplus funds, part-prepayment remains a good option to reduce principal and interest outgo over time.
- Review your loan statement at the next reset date to confirm no other changes have been applied.
Tips for Those Planning New Loans or FDs
- Compare home loan and personal loan offers across banks, as pricing can still differ.
- For FDs, current rates can be locked in if they meet your return expectation.
- Avoid rushing into large new loans or long-tenure FDs solely on the basis of today’s decision; focus on your overall financial plan.
Why RBI Took This Decision – Key Factors
Inflation Outlook
The MPC has been closely watching the inflation trajectory. Keeping the rate unchanged suggests the committee is comfortable waiting for more data before deciding on any tightening.
Growth and Global Factors
Domestic growth has remained resilient. At the same time, global uncertainties, including crude oil prices and international financial conditions, continue to influence the policy calculus. The neutral stance allows the RBI to respond as the picture becomes clearer.
Frequently Asked Questions on RBI MPC Decision Today
Has RBI increased the repo rate today?
No. The repo rate has been kept unchanged at 5.25%.
Will my home loan EMI increase immediately?
No. With the repo rate unchanged, there is no policy-driven reason for an immediate increase in floating-rate home loan EMIs.
When will banks revise FD rates?
Banks revise FD rates based on their own funding needs and market competition. Today’s decision does not force an immediate across-the-board increase.
Is the policy stance still neutral?
Yes. The MPC has retained its neutral stance.
How soon will loan rates change after the decision?
Since the repo rate itself has not changed, loan rates are not expected to move solely because of today’s announcement. Any future change will depend on subsequent policy actions or bank-level decisions.
Summary – What Today’s RBI Decision Means for You
The RBI has kept the repo rate unchanged at 5.25% and retained a neutral stance. For home loan and personal loan borrowers, this means no immediate increase in EMIs linked to the policy rate. For depositors, FD rates are likely to stay largely stable in the near term.
The decision provides continuity. Borrowers get breathing space, while depositors will need to watch individual bank actions for any rate improvements. As always, the actual impact on your finances will depend on how your bank transmits (or does not transmit) policy signals and on your own loan or deposit terms.